Per stirpes divides your estate by branch, so a grandchild steps into a deceased parent’s share; per capita divides it by head count among survivors, cutting out that branch entirely. If you want grandchildren protected, choose per stirpes. If you want equal shares among whoever’s alive when you die, choose per capita. Either way, verify how your bank, insurer, or attorney actually defines the term before you sign anything.
- Choosing per stirpes protects grandchildren from disinheritance if their parent predeceases you, whereas per capita distributes only among surviving named beneficiaries.
- State law defaults and account custodian definitions can differ significantly, so reviewing and clarifying how each interprets these terms is essential.
- Many beneficiary forms exclude grandchildren unless explicitly specified as “per capita at each generation,” which can unintentionally disinherit entire branches.
- Discrepancies between will language and account forms often lead to unintended outcomes unless thoroughly cross-checked and updated regularly.
- Professional review and coordination of estate documents and beneficiary designations can prevent costly mistakes rooted in misunderstood Latin terms.
Per Stirpes vs. Per Capita: What “By Branch” Actually Means
Per stirpes comes from Latin for “by the branch” or “by roots.” Under this method, if one of your named beneficiaries dies before you, that person’s share doesn’t get absorbed by the surviving beneficiaries. It drops straight down to their own children, keeping the branch intact.
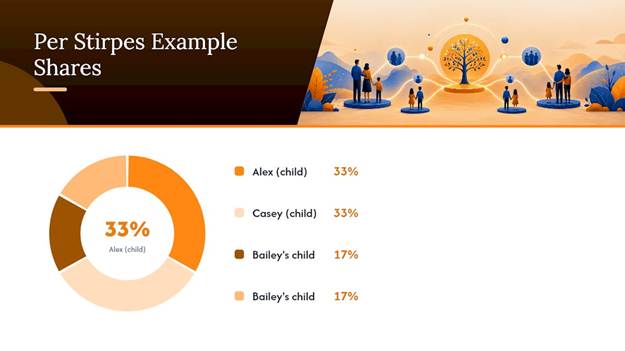
Here’s the math. Say you have three children: Alex, Bailey, and Casey, and you leave your estate to them equally per stirpes. Bailey dies before you, leaving two kids of their own.
- Alex receives one third of the estate.
- Casey receives one third of the estate.
- Bailey’s one third gets split between Bailey’s two children, one sixth each.
Your two grandchildren inherit exactly what their parent would have gotten, split evenly between them. Nobody outside Bailey’s line gets a bigger cut just because Bailey died first.
Insight: Per stirpes is commonly assumed as the default on many standard will templates, and for good reason. It matches what most parents actually intend: keep the money in each child’s family line, even if that child doesn’t live to inherit it directly.
Practitioners at University of Louisville’s law program note that per stirpes is generally the recommended structure when a testator wants grandchildren shielded from accidental disinheritance. If you have children and expect grandchildren someday, this is usually the safer default, not an afterthought.
Per Stirpes vs. Per Capita: What “By Head” Actually Means
Per capita is Latin for “by the head.” Instead of passing a deceased beneficiary’s share down to their kids, the estate gets divided equally among whoever in the named class is still alive when you die. If someone in that group has already died, their share doesn’t disappear. It gets redistributed among the survivors, not their descendants.
Run the same family through this method. Alex, Bailey, and Casey are named per capita, and Bailey dies before you, leaving two children.
- Alex receives one half of the estate.
- Casey receives one half of the estate.
- Bailey’s two kids receive nothing under this distribution, because per capita only counts surviving members of the named group.
That’s the fork in the road. Same family, same facts, wildly different outcome depending on one Latin phrase in your will.
LegalClarity’s breakdown of beneficiary designations points out that per capita fits situations where you want equal shares among living people rather than passing anything to their descendants, such as leaving assets equally to siblings or close friends with no expectation their children inherit in their place. But per capita isn’t one fixed rule. Depending on the document, it can mean per capita among surviving named beneficiaries only, per capita among all surviving descendants regardless of generation, or per capita at each generation, a modern hybrid that changes the math again.
Comparing the Two Side by Side
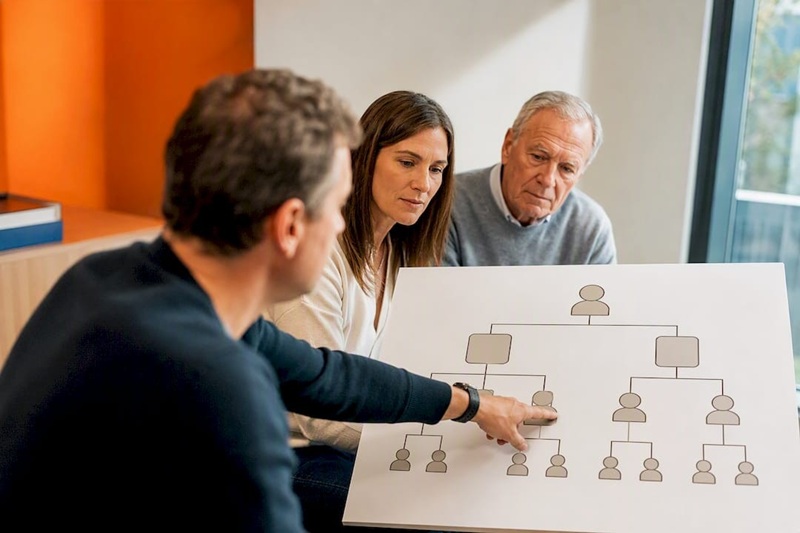
Picture the family tree laid out plainly. You have three children, one of whom died before you and left two kids behind.
Per stirpes: Estate splits into three branches at your children’s generation. Alex gets 1/3, Casey gets 1/3, and Bailey’s branch keeps its 1/3, split 1/6 and 1/6 between Bailey’s two children.
Per capita (strict): Estate splits only among the living. Alex gets 1/2, Casey gets 1/2. Bailey’s children get zero.
Per capita at each generation: Estate splits equally at the nearest generation with survivors, then any remaining share drops evenly to the next generation. In this example, Alex and Casey would take shares at the top level, and Bailey’s portion would still flow to their children, but the exact split depends on how many others exist at each generation.
The counterintuitive part trips up a lot of people: many assume “per capita” automatically means grandchildren inherit their parent’s spot. It doesn’t, unless the document specifies “per capita at each generation” or “with representation.” Assuming otherwise is how entire branches of a family get quietly disinherited.
| Factor | Per Stirpes | Per Capita (Strict) |
| Protects grandchildren if a child predeceases | Yes | No, unless representation is specified |
| Equal treatment among survivors | No, shares depend on branch | Yes, split evenly among survivors |
| Administrative complexity | Moderate, tracks generations | Low to moderate, depends on variant used |
| Common use case | Parents with children and grandchildren | Equal gifts to siblings, friends, or unrelated individuals |
| Risk of unintended disinheritance | Low | Higher if intent isn’t spelled out |
- Per stirpes keeps money inside a bloodline even after a parent’s death.
- Per capita rewards whoever survives, which can accidentally exclude an entire family unit.
- The “per capita at each generation” variant tries to split the difference but adds real complexity to drafting and administration.
Why State Law and Modern Statutes Matter Here
If your will or trust doesn’t specify a method, state law fills the gap, and that default varies. Many states have moved toward what’s often called “modern per stirpes” or “per capita with representation,” an approach shaped by the Uniform Probate Code.
- Modern per stirpes divides the estate at the first generation with a living member, not automatically at your children’s generation, which can shift outcomes if your oldest child died with no descendants.
- Per capita with representation aims to equalize what grandchildren receive across different branches, even when one branch has more surviving descendants than another.
- Wikipedia’s summary of per stirpes law confirms that many U.S. jurisdictions have adopted these representation-based defaults instead of the older strict version.
The practical takeaway: silence in your will doesn’t mean the outcome is neutral. It means a judge applies whatever your state’s default happens to be, and that default might not match what you actually wanted. If you’re unsure how your state fills that gap, that’s exactly the kind of question to raise when reviewing wills and trusts in Illinois or your own state’s equivalent statute.
Where You Actually Choose: Wills, Trusts, and Beneficiary Forms
The words “per stirpes” or “per capita” don’t live in one place. They show up in your will’s residuary clause, your trust’s distribution language, and the beneficiary designation fields on your 401(k), life insurance policy, and bank accounts. Each one can be set independently, and that’s where things go sideways.
- Check your will’s residuary clause for the exact term used, not just an assumption about what “should” happen.
- Check your trust’s distribution provisions separately. They don’t automatically mirror your will.
- Check every beneficiary form on every account. Insurers and custodians often interpret these terms differently than your attorney does.
- Name contingent beneficiaries everywhere, not just primary ones.
- Ask your custodian directly what happens if a primary beneficiary predeceases you.
A Journal of Insurance Regulation study published through NAIC found that insurers, estate attorneys, and financial planners don’t consistently apply the same definition of per capita. That gap has real consequences: a policy can distribute funds in a way that contradicts what your will says, simply because the insurance form used a narrower definition.
Insight: Get your custodian’s definition in writing, even a screenshot of the form’s fine print, before you rely on it. If the language is vague, add explicit instructions in the additional comments field rather than trusting the Latin term alone.
Also worth knowing: most states apply a 120-hour survival rule, meaning a beneficiary must outlive you by five days to inherit at all. If they don’t, they’re treated as having predeceased you, which can trigger per stirpes or per capita calculations you didn’t expect.
How to Choose Between Per Stirpes and Per Capita
Start with your family structure, not the legal term. The decision usually comes down to a handful of concrete questions.
- Do you have grandchildren, or expect to? Per stirpes protects them if a child dies first.
- Are your named beneficiaries unrelated to each other, like siblings or friends? Per capita may match your intent better.
- Do you have a blended family with stepchildren who aren’t legally adopted? This is where ambiguous Latin terms cause the most damage, since “descendants” may not include stepchildren without explicit language.
- Would you be comfortable if one branch of your family received nothing because that beneficiary happened to survive you?
Take these questions to your attorney and to each account custodian:
- How does your firm define per capita on this specific form?
- What happens if my named beneficiary dies before me but their children are still alive?
- Does this account’s beneficiary form recognize per stirpes designations at all, or only percentages?
- What’s your default if I leave this field blank?
Red flags that mean you need an attorney now, not later: you have children from more than one relationship, you’ve adopted or are raising stepchildren without formal adoption, or your will and your beneficiary forms use different distribution language. Updating a will or trust to fix distribution language typically takes a few weeks once you’ve had an initial consultation, and flat-fee estate planning services often bundle beneficiary form review into that same engagement rather than billing separately for it.
Common Mistakes That Undo Good Intentions
- Leaving beneficiary forms blank or letting them use different wording than your will.
- Failing to name contingent beneficiaries, which forces probate court to guess your intent.
- Assuming per capita automatically includes grandchildren the way per stirpes does. It doesn’t, unless the form says “with representation.”
- Never asking your bank or insurer how they define these terms internally.
Pro Tip: Set a recurring reminder, once every two to three years or after any major family change, to pull every beneficiary form you have and read the actual language, not just the account balance.
The fix is almost always the same: read every distribution clause and beneficiary form side by side, and correct any mismatch immediately rather than assuming they’ll sort themselves out later. Learn more about how beneficiary rights work if a form gets this wrong.
How Chosen Estate Planning Helps Clients Decide and Implement
We start every engagement with a plain-language conversation about your actual family, not a checklist of legal terms. That’s how we catch the details generic forms miss, like a stepchild you consider your own or a grandchild born after your last will was signed.
From there, our flat-fee process covers document drafting, a review of existing beneficiary designations, and an opportunity to check with your account custodians to confirm how they define per stirpes or per capita on their specific paperwork. Blended families, unmarried partners, and anyone with a complex beneficiary line benefit most from this kind of hands-on review, since these are exactly the situations where ambiguous Latin terms cause the most damage. Our guide to estate planning for blended families covers more of what that looks like in practice.
The Conventional Advice Skips the Part That Matters Most
Most articles on this topic stop at definitions. They’ll tell you per stirpes protects grandchildren and per capita treats survivors equally, then leave you to figure out implementation on your own. That’s backwards. The definitions are the easy part. The part that actually causes problems is the gap between what your will says and what your beneficiary forms say, and almost nobody checks that gap until it’s too late.
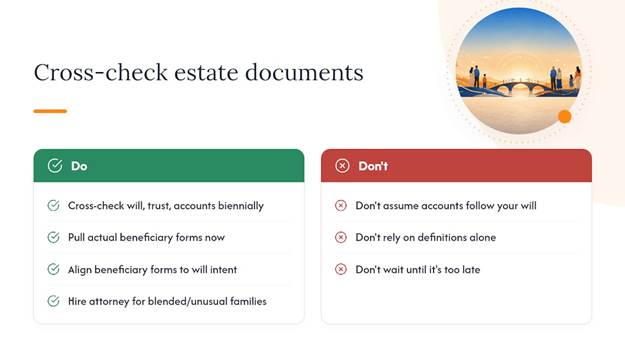
I’d argue the real skill here isn’t picking the right Latin term. It’s building the habit of cross-checking every document that touches your estate, your will, your trust, your 401(k), your life insurance, against each other every couple of years. A perfectly drafted will means nothing if your insurance form defaults to a narrower definition of per capita than you intended.
If you take one thing from this article, make it this: don’t trust that your accounts inherited your will’s intent automatically. Go pull the actual forms. If you have a blended family or any beneficiary whose status is even slightly unusual, that’s the moment to bring in an attorney rather than guess.
Get Your Distribution Method Written Into Every Document, Not Just Your Will
Chosen Estate Planning removes the guesswork of implementation with flat-fee pricing that covers your will, trust, and beneficiary form review in one engagement, so you’re never stuck paying by the hour to fix a mismatch you didn’t know existed.
We walk through your actual family structure in plain language, then draft distribution clauses that hold up consistently across every account and document you own, including a direct check with your custodians on how they define these terms. If you’re ready to lock in the right method for your family, schedule a flat-fee consultation and get it handled correctly the first time. Prefer to explore on your own first? Download our Chosen Family Estate Plan e-book for a low-commitment starting point. And if your estate includes real property with multiple heirs, this guide to selling inherited property with multiple owners is worth a look before you finalize anything.
To get started, book a discovery call or download the Chosen Family Estate Plan e-book for a plain-language overview of your options.
This article is general information, not a substitute for advice from a qualified lawyer. Consult a qualified legal professional about your own circumstances before acting on anything here.
Sources
- Stirpes distributions and estate planning (University of Louisville)
- Per Stirpes vs Per Capita in beneficiary designations (LegalClarity)
- Life Insurance Beneficiaries – Per Capita vs. Per Stirpes: Is It Really That Clear? (Journal of Insurance Regulation / NAIC)
- Per stirpes (Wikipedia)
Recommended